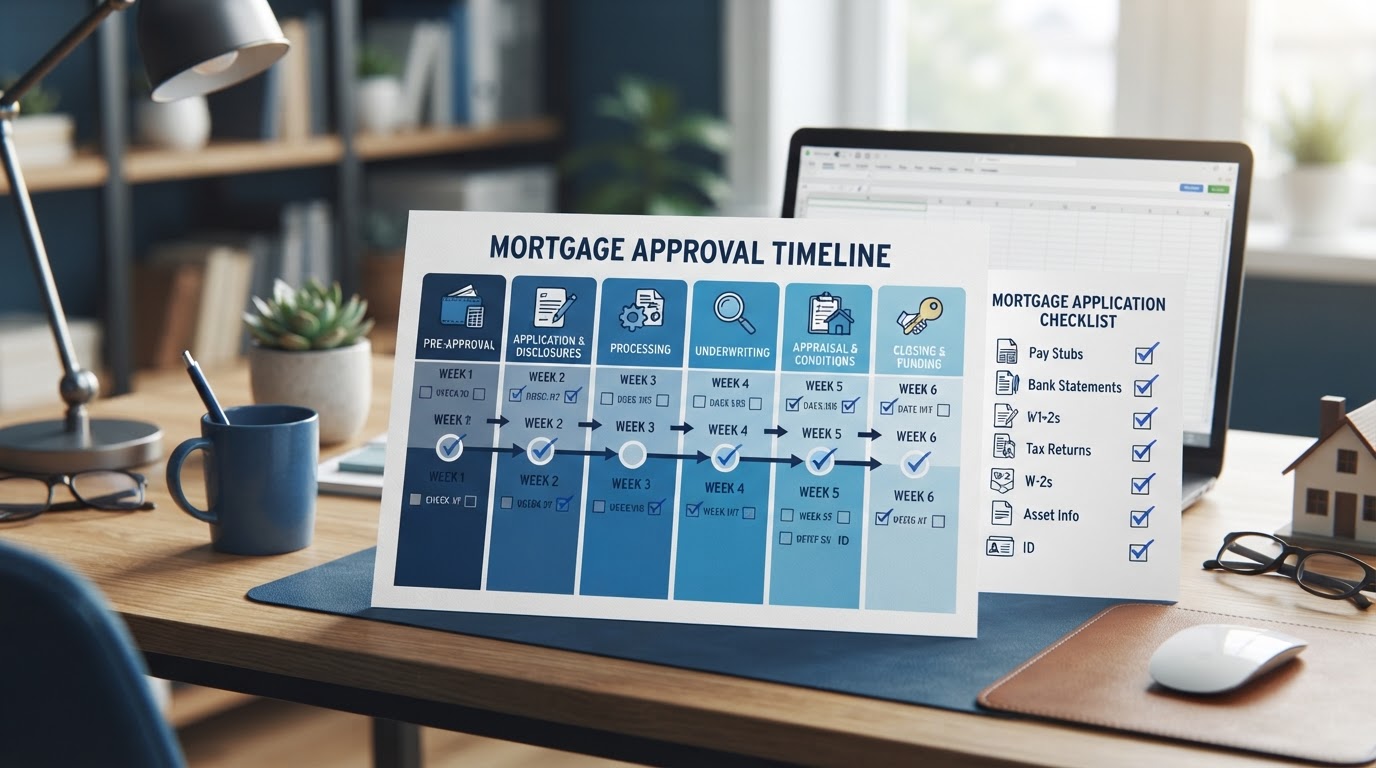
One of the most common questions buyers ask is, "How long does mortgage approval take?" The timeline varies based on your situation, the lender, the property and the market, but understanding the steps can help you plan. This guide walks through the mortgage approval timeline from application to closing.
The short answer: the mortgage process typically takes several weeks from application to closing, with the timeline depending on document collection, appraisal, underwriting and your responsiveness. These are typical ranges, not guarantees.
1. Application and document collection
The process starts when you apply and provide your documents. Common documents include:
- Photo ID
- Recent pay stubs
- W-2 forms and federal tax returns
- Bank statements
- Information about your debts
The faster you provide complete documents, the faster your loan moves. This step can take a few days to a week, depending on how quickly you respond.
2. Credit review and pre-approval
The lender reviews your credit and your documents to understand what you may qualify for. If you are already pre-approved, this step can be faster. Read our mortgage pre-approval checklist to prepare.
3. Appraisal
After you have a contract on a home, the lender orders an appraisal to confirm the property's value supports the loan amount. The appraisal is usually scheduled within a week or two, and the report can take a few more days to come back.
4. Underwriting
Underwriting is the lender's detailed review of your file. The underwriter checks your credit, income, assets and the property to confirm everything meets the loan program's requirements. Underwriting can take several days to a couple of weeks, depending on the complexity of your file and the lender's volume.
5. Conditions and clear to close
The underwriter may issue conditions, which are items you need to satisfy before closing, such as:
- An updated pay stub
- A letter of explanation for a credit item
- A repair or inspection item on the property
Once you satisfy the conditions, the lender issues a clear to close, which is the final approval that schedules your closing.
6. Closing
At closing, you sign your final documents, pay your closing costs and take ownership of the home. Closing is usually scheduled a few days after the clear to close.
Typical timeline overview
These are typical ranges, not guarantees:
- Application and document collection: a few days to a week
- Credit review and pre-approval: a few days
- Appraisal: one to two weeks
- Underwriting: several days to a couple of weeks
- Conditions and clear to close: a few days to a week
- Closing: a few days after clear to close
The total timeline can vary based on how quickly you respond, the complexity of your file, the property and the lender's volume.
How to speed up your mortgage approval
- Respond to your lender's requests quickly.
- Provide complete and accurate documents the first time.
- Avoid new credit, large purchases or job changes during the process.
- Keep your finances steady until closing.
- Stay in touch with your loan officer and ask about anything you do not understand.
Frequently asked questions
How long does the whole mortgage process take? The process typically takes several weeks from application to closing, depending on your situation, the property and the lender.
What slows down mortgage approval? Common delays include missing documents, new credit activity, appraisal issues and complex income such as self-employment.
What is a clear to close? A clear to close is the lender's final approval, meaning your loan is approved and your closing can be scheduled.
Can I close faster? A faster timeline is possible when documents are complete, the appraisal goes smoothly and you respond quickly to your lender's requests.
Ready to start your application?
When you are ready, get a free quote or get pre-approved with Alex.
You can also call Alex Al-Ammar at (313) 992-9898 or email Alex@vestalending.com.
This article is for general information only. It is not legal, tax or financial advice. Timelines are typical ranges and not guarantees. Speak with a qualified professional about your individual situation.


