When you choose a mortgage, one of the first decisions is whether you want a fixed-rate or an adjustable-rate mortgage. Each has different risks and benefits, and the right choice depends on how long you plan to stay in the home, your budget and your comfort with risk.
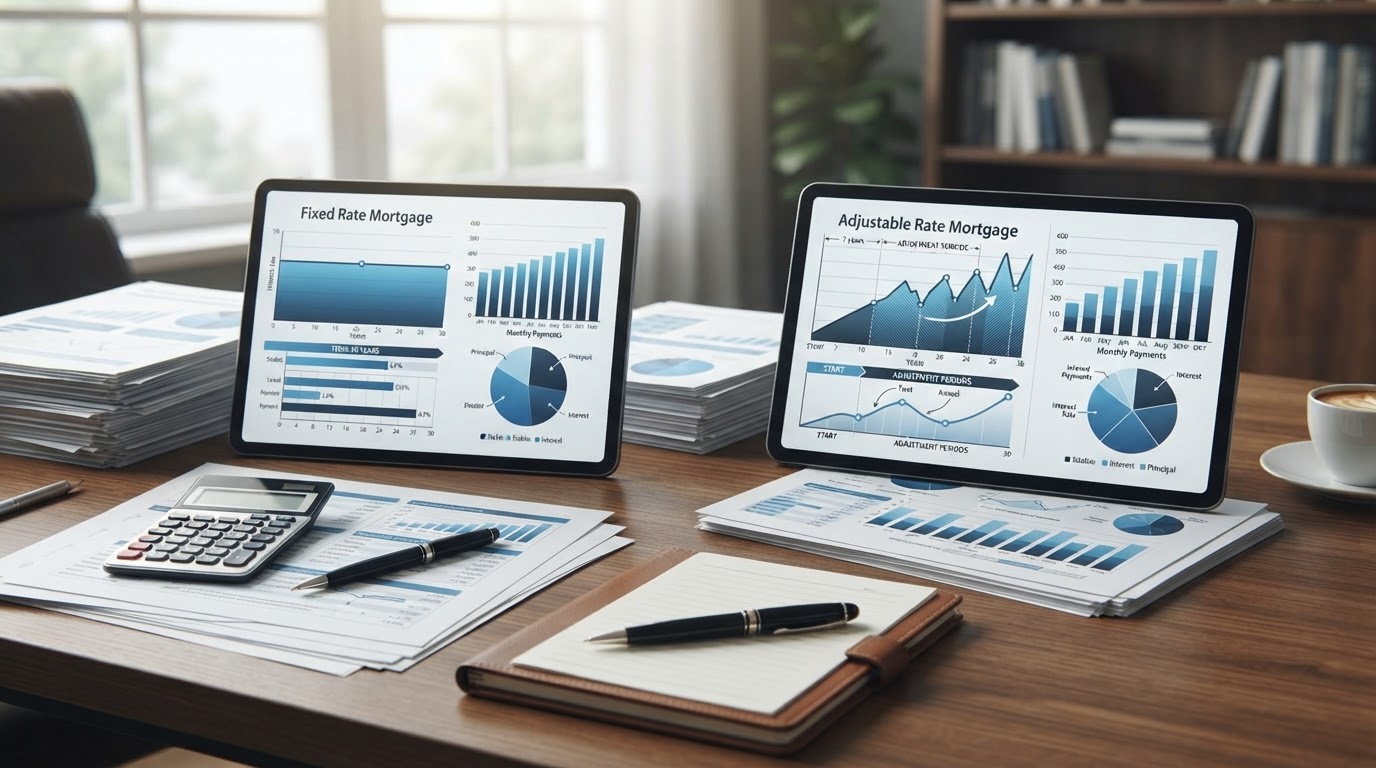
The short answer: a fixed-rate mortgage keeps the same interest rate for the life of the loan, so your principal and interest payment stays the same. An adjustable-rate mortgage (ARM) has a rate that can change after an introductory period, which can lower your payment early but raise it later. Learn more on our fixed-rate mortgage page.
What is a fixed-rate mortgage?
A fixed-rate mortgage has an interest rate that stays the same for the entire loan term. Your principal and interest payment never changes, which makes budgeting easier.
Common terms include 15, 20 and 30 years. A longer term usually means a lower monthly payment but more total interest paid over the life of the loan. A shorter term usually means a higher monthly payment but less total interest.
What is an adjustable-rate mortgage?
An adjustable-rate mortgage (ARM) has an interest rate that can change over time. ARMs typically start with an introductory period during which the rate is fixed, after which the rate adjusts on a set schedule based on a market index.
For example, a "5/1 ARM" has a fixed rate for the first five years, then adjusts once per year after that.
Key differences
Rate stability
- Fixed-rate: your rate and your principal and interest payment stay the same for the life of the loan.
- ARM: your rate can change after the introductory period, which can raise or lower your payment.
Introductory rate
ARMs often start with a lower introductory rate than a comparable fixed-rate loan. That lower rate can make the early years more affordable, but it can also change.
Adjustment period
After the introductory period, an ARM adjusts on a schedule. Each adjustment is based on an index plus a margin, and the loan usually has caps that limit how much the rate can change at each adjustment and over the life of the loan.
Risk
- Fixed-rate: predictable, with no risk of payment increases from rate changes.
- ARM: your payment can rise after the introductory period, which can make budgeting harder if rates go up.
Total cost
The total cost depends on how long you stay in the home and how rates change. If you sell or refinance before the ARM adjusts, you may benefit from the lower introductory rate. If you stay longer, a rising rate can increase your costs.
How to compare fixed and adjustable rates
- Think about how long you plan to stay in the home.
- Compare the introductory rate of the ARM with the fixed rate.
- Ask about the ARM's caps, index and margin.
- Consider how your budget would handle a higher payment if the rate rises.
- Compare the total cost over the time you expect to own the home.
Which is right for you?
A fixed-rate mortgage may fit if you want predictable payments and plan to stay in the home for a long time. An ARM may fit if you plan to move or refinance before the rate adjusts and you are comfortable with the risk.
There is no single best choice. A licensed loan officer can run the numbers for your situation and help you compare.
ARM terms explained: initial period, index, margin, caps
If you are considering an ARM, here is what each term means:
- Initial period: the years your rate is fixed before the first adjustment. For example, a 7/6 ARM is fixed for 7 years, then adjusts every 6 months.
- Index: the market rate your loan follows (such as SOFR).
- Margin: the lender's added percentage on top of the index. Your adjusted rate is the index plus the margin.
- Caps: limits on how much the rate can rise per adjustment and over the life of the loan. Caps protect you from large jumps but do not eliminate risk.
Ask your lender for the specific index, margin and caps on any ARM you consider.
Side-by-side comparison
| Feature | Fixed-Rate | ARM |
|---|---|---|
| Rate | Never changes | Fixed then adjusts |
| Payment | Predictable | Can rise or fall |
| Early years | Usually higher rate | Often lower introductory rate |
| Best for | Long-term owners | Short-term owners |
Who may consider an ARM
An ARM may fit if you:
- Plan to sell or refinance before the fixed period ends
- Are comfortable with some rate risk
- Want a lower initial payment
Ask yourself: can I afford the payment if the rate rises to the cap? If the answer is yes and you plan to move before the ARM adjusts, an ARM may be worth considering.
Frequently asked questions
Can my ARM payment go down? Yes. After the introductory period, an ARM rate can go up or down based on the index, within the loan's caps.
What are ARM caps? Caps limit how much your rate can change at each adjustment and over the life of the loan. Ask your lender for the specific caps on any ARM you consider.
Is a fixed-rate mortgage always safer? A fixed rate gives you predictable payments, but it is not always the lowest-cost option. The right choice depends on your plans and comfort with risk.
Can I refinance from an ARM to a fixed rate later? Yes, if you qualify. Refinancing depends on your credit, home value and market rates at the time. See our refinance page to learn more.
Ready to compare your options?
When you are ready, get a free quote or get pre-approved with Alex.
You can also call Alex Al-Ammar at (313) 992-9898 or email Alex@vestalending.com.
This article is for general information only. It is not legal, tax or financial advice. Loan programs, rates and requirements depend on your credit, income, property and lender. Speak with a qualified professional about your individual situation.